- Barrick would contribute Fourmile and Newmont would bring in Fiberline and Mike.
- The agreement provides for $1.95 billion from Newmont to Barrick.
- Partner consent is one step in a proposed North American listing.
Inside this story 2 perspectives
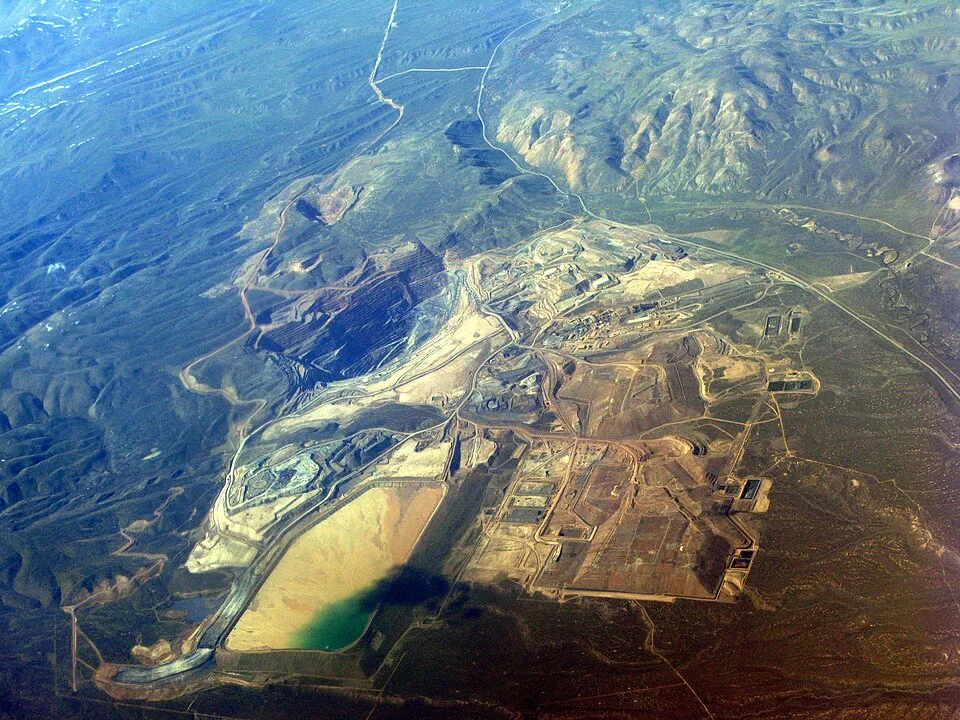
A mining company preparing to list a business on the stock exchange has to explain precisely what a new shareholder would own. On 10 August Barrick and Newmont redrew a boundary that matters to that explanation. Three developments previously kept outside their Nevada Gold Mines joint venture would now go into it. The two companies said they had settled all outstanding disputes with each other relating to the venture.
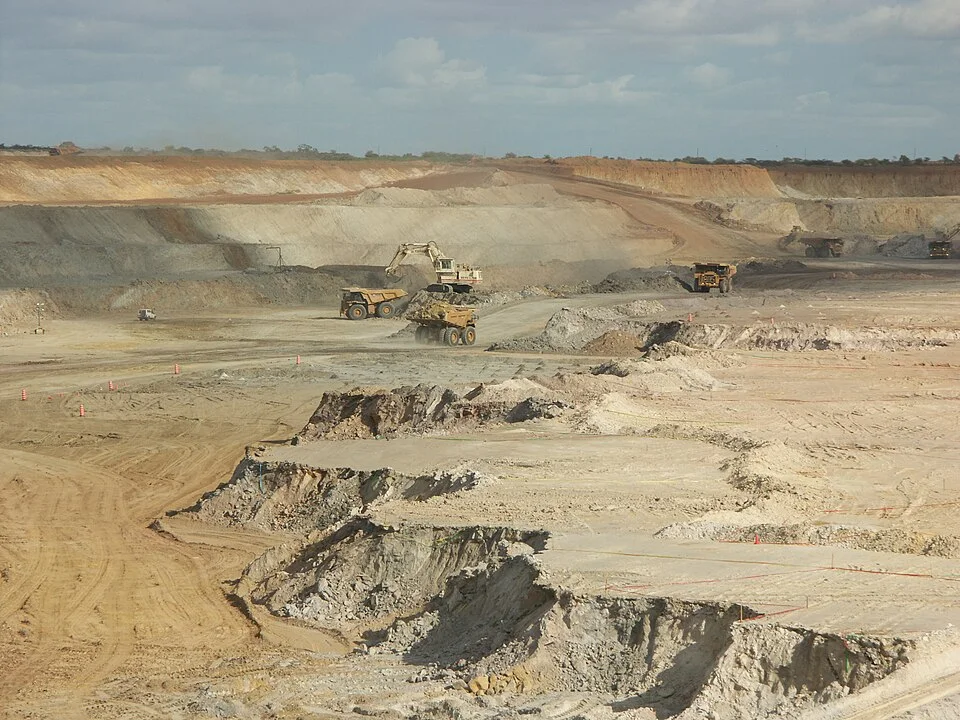
Barrick would contribute Fourmile. Newmont would bring in Fiberline and Mike. The agreement provides for $1.95 billion from Newmont to Barrick to reflect the assets contributed. It also brings Newmont’s consent for Barrick’s proposed initial public offering of its North American gold assets. Those are distinct outcomes of the negotiation. The payment addresses the balance of the property contributions, while consent addresses what Barrick can do with its own business.
The significance of the line on the map
In a joint mining enterprise, a boundary can affect much more than the name on an exploration licence. A property on one side may be developed inside a shared operation, where partners have agreed how to make decisions. On the other side, one partner might control the project separately. Even if the ground lies in the same part of the world and contains the same commodity, an investor needs to understand which people can commit funds and on what terms.
The companies said they had updated the governance arrangements as part of the agreement. They also described potential improvements to safety, operating performance and long-term value. Those statements set out what the owners hope to achieve together. Bringing developments into the same venture does not itself deliver a tonne of ore, settle the cost of development or determine when a project will start to contribute to production.
What the proposed listing still has to answer
Consent from an important partner removes a defined source of uncertainty. It gives investors a clearer starting point for evaluating the proposed business. It leaves other questions open, including the timing and structure of an offering, approvals, market conditions and the disclosures potential shareholders will use to assess the assets. The companies identified several of those factors in their announcement.
For anyone comparing a mining group with a future separately traded business, the distinction is consequential. A corporate chart might place several properties under a common heading, yet the asset interests and rights attached to each still determine what an investor would participate in. August’s agreement brings the map and the governance closer together. The eventual listing documents, if the offering proceeds, will have to show what that arrangement means in financial terms.