- The bank and ODI announced a research and policy agreement in Abidjan.
- They will examine guarantees, insurance and methods for moving assets off lenders’ books.
- The agreement identifies questions about affordable finance and makes no new project loan.
Inside this story 2 perspectives
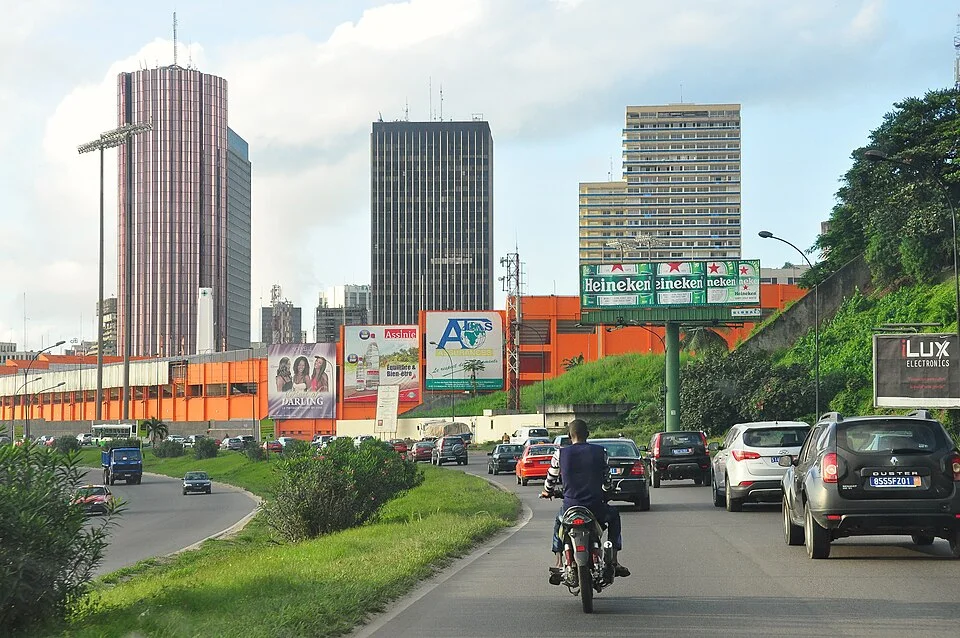
Imagine two offers to lend to the same infrastructure project. One carries a lower interest rate because a third party has agreed to cover some losses if the borrower cannot repay. Which offer is cheaper? The answer depends partly on who pays for the guarantee, what losses it covers and who would have borne them otherwise. Those questions sit inside an agreement announced in Abidjan on 6 October by the African Development Bank Group and ODI Global.
The institutions will bring the bank’s experience with actual operations together with independent policy research. Their remit includes guarantees and insurance, as well as the use of funds offered on favourable terms and ways of getting private investors to participate. The announcement establishes a programme of work. It does not assign money to a particular road, power project or borrower.
Following one risk through the accounts
A guarantee can bring in a lender that would otherwise decline a project. It can also help an existing lender offer a longer repayment period. The borrower may gain time for an asset to start earning revenue before a large payment falls due. The guarantor, meanwhile, takes on a potential obligation. Whether the combination represents a good use of scarce resources depends on the prospective loss, the fee and the benefit of the project going ahead.
That is where comparing completed transactions can be more revealing than adding up the announced value of guarantees. If a lender would have financed a project on similar terms anyway, a small reduction in interest has a different significance from a guarantee that made a previously unavailable loan possible. The institutions’ published plans include comparing financial instruments and the experience of development lenders dealing with governments and private borrowers.
The next loan matters too
The partnership will also examine arrangements that move part of a loan portfolio away from a development bank’s balance sheet. In principle, another investor can take a share of existing exposure and leave the bank room to finance additional work. The relevant follow-up is what the bank then does with that capacity. A transfer on its own says little about the terms eventually offered to the next borrower.
Governments face pressing financing needs alongside higher borrowing costs and competing demands for concessional resources. That gives the partnership a fairly precise test for its eventual findings. Can a finance ministry or project sponsor use them to compare the total cost and risks of two real offers? An answer that identifies the fee, the protection and the remaining risk would tell a borrower more than an assurance that a tool can attract private money.